


Dear Weekender,
Recently, the Financial Intelligence Unit (FIU) Sint Maarten organized trainings on preventing money laundering, terrorist financing and proliferation financing. The sessions were held for accountants, tax advisers and administration offices, as well as for lawyers and attorneys. Drawing on the presentation prepared by ComplianceAid, we would like to share some of the points discussed and explain why they matter to service providers and their clients.
From paper to practice
A recurring message was that compliance requires more than having policies on paper. It requires understanding risks, asking questions and acting when something does not add up. For professionals who assist with business structures, financial records and tax matters, these responsibilities form part of protecting both their practices and Sint Maarten’s financial system.
One important discussion concerned the assessments conducted by the Caribbean Financial Action Task Force. These evaluations consider whether a country has the necessary laws and institutions, but also whether its arrangements work effectively. Having legislation is one step; demonstrating that businesses identify risks, apply controls and report unusual transactions is another.
The trainings highlighted weaknesses such as uneven implementation across sectors, insufficient risk-based controls and weak reporting in non-financial businesses. They also addressed gaps in understanding sanctions and proliferation financing. These findings show why compliance cannot be approached as a checklist completed once and then filed away.
Know your customer
For service providers, this means looking carefully at each customer and business relationship. Customers do not all present the same risk. An unclear ownership structure, unusual payment arrangement or activity inconsistent with a customer’s business may require further questions.
Customer due diligence should therefore develop as circumstances change, with additional checks where the risk justifies them.
Identifying the beneficial owner, meaning the person who ultimately owns or controls a business, is particularly important. Knowing the company’s name alone may provide an incomplete picture. Professionals also need to understand the purpose of the relationship and recognize connections between transactions. Clear documentation helps explain what was checked, what concerns arose and how decisions were reached.
Recognizing and reporting risks
Another key point was unusual transaction reporting. The trainings explained that limited reporting from an exposed sector can suggest that risks are being missed or concerns are not being escalated. Employees should know which warning signs to recognize, whom to approach internally and how the reporting process works.
Attention was also given to proliferation financing, which can arise through sanctioned parties, hidden ownership, cross-border trade and restricted goods or jurisdictions. Although these risks may appear distant from everyday tax work, professional services can intersect with the structures and transactions involved. Awareness, appropriate screening, and clear escalation procedures are therefore important parts of a broader compliance program.
Procedures and the people behind them
Strong internal controls provide the practical foundation for addressing these concerns. The trainings discussed written procedures, customer checks, ongoing monitoring, reporting processes and staff training. Procedures should be understandable, regularly updated and suited to the business. Employees need guidance they can use when information is missing, a transaction appears unusual or a customer’s explanation raises further questions.
However, procedures depend on the people responsible for implementing them. Business owners and boards oversee compliance, while senior management establishes the culture within the organization. A compliance officer needs independence and authority to carry out the role effectively. Staff should feel comfortable raising concerns and should be protected when they do so. A culture that places sales above compliance undermines these efforts.
Safeguards and inspection readiness
Practical safeguards discussed included separating responsibilities, requiring approvals, monitoring activities and conducting internal reviews or independent testing. Regular training should reflect employees’ roles and help them recognize relevant risks. Secure and accessible records are equally essential. Customer information, transaction records, reporting documentation and training logs help demonstrate that the compliance program operates throughout the year.
These arrangements also prepare businesses for FIU inspections. Firms should be able to explain their risk assessments, present customer files and demonstrate monitoring, oversight and corrective action. Inspection readiness should grow naturally from sound daily practices rather than depend on hurried preparations when a visit is expected.
A shared responsibility
For clients, this helps explain why professional service providers ask for identification, ownership information or clarification about transactions. Cooperation enables advisers to understand the business relationship and fulfil their responsibilities. Complete and accurate information supports a more efficient process while helping protect the integrity of the services being provided.
The message from the trainings was clear: Effective compliance depends on shared responsibility. Through informed staff, engaged leadership, stronger controls and cooperation with the FIU, professional service providers can contribute to a more resilient financial system. Clients, in turn, play their part by providing information and understanding why these checks matter.
We would like to thank the FIU for organizing these trainings. We also encourage service providers to take this opportunity to review their own risk assessments, customer files and internal procedures. Should you have any questions about these obligations, whether as a service provider or as a client, please do not hesitate to contact us.
Yours sincerely,
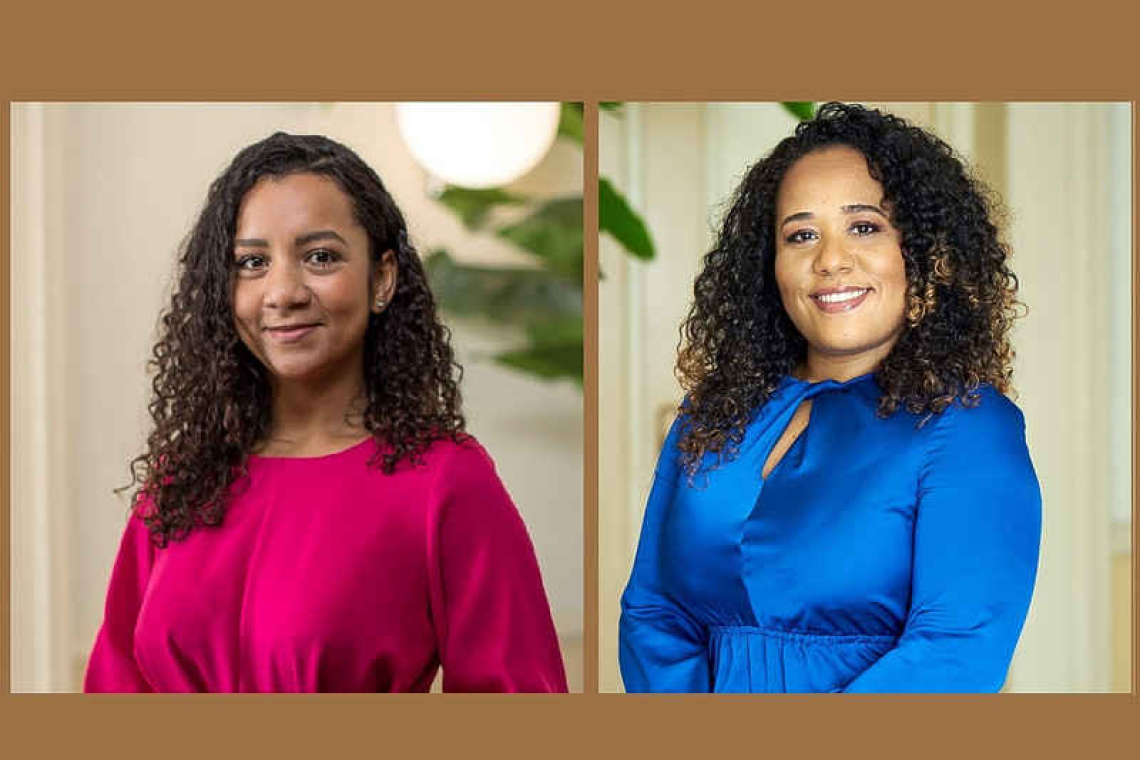
Estherina Garcia & Nicole Echobardo | HBN Law & Tax
This email address is being protected from spambots. You need JavaScript enabled to view it., This email address is being protected from spambots. You need JavaScript enabled to view it.